

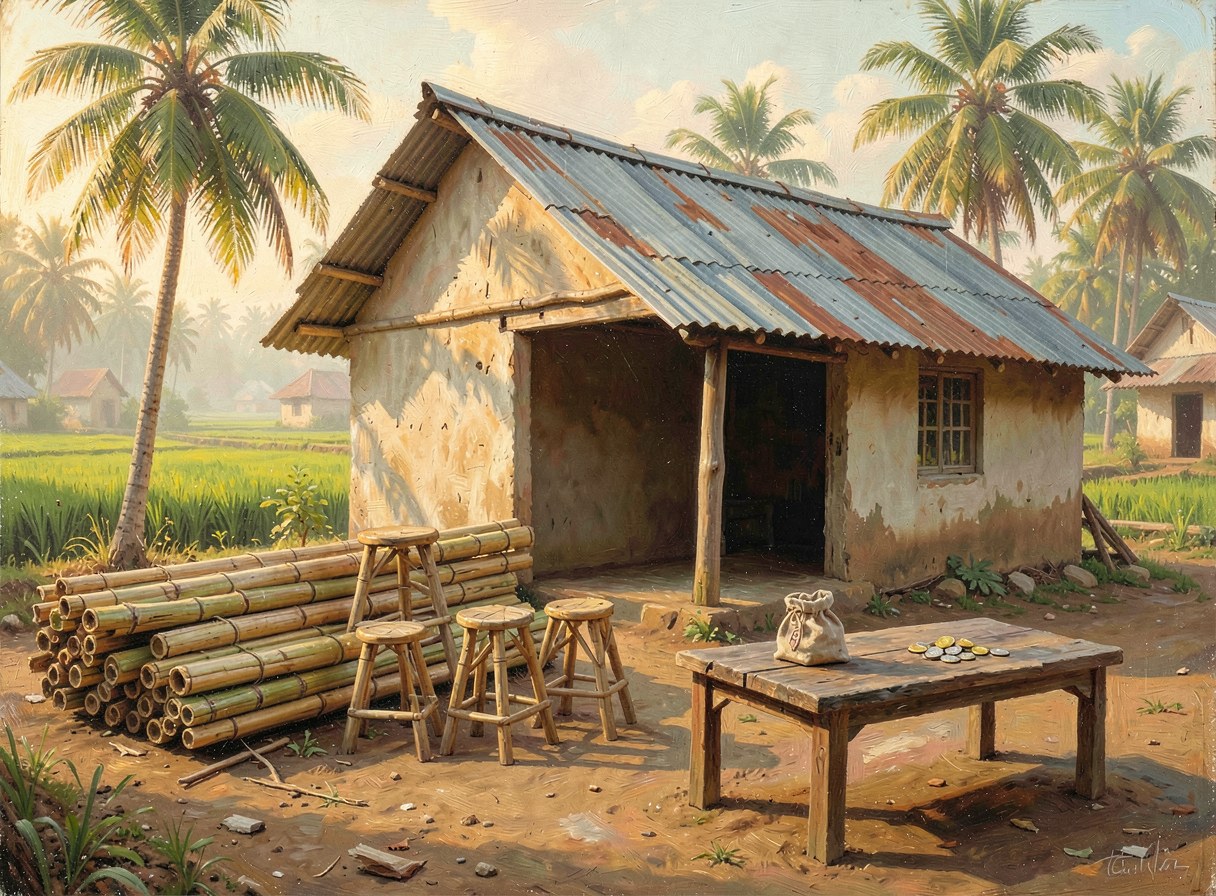
It began not with a treaty or a ceasefire, but with a question asked in a dusty village in Bangladesh. In 1976, economist Muhammad Yunus was grappling with a famine and found himself wondering: What if the problem wasn’t a lack of ability, but a lack of trust? What if the only thing standing between a capable person and a better life was a door marked “No Collateral, No Credit”? His answer was an audacious experiment—he lent $27 of his own money to a group of 42 women to buy bamboo for making stools. They repaid every cent.
This small, defiant act of faith in human potential was the seed of Grameen Bank and, three decades later, the reason its founder and the institution he built would share the Nobel Peace Prize. The committee’s citation was revolutionary in its own right, awarding the prize “for their efforts to create economic and social development from below.” In that phrase, they declared a profound idea: peace is not merely the absence of war, but the presence of dignity, opportunity, and security for all. They placed a bank in the same lineage as peacekeepers and treaty negotiators, arguing that the most sustainable way to build a stable world is to empower its people from the ground up.
The Architecture of Trust: More Than Just a Loan
Yunus’s initial insight was deceptively simple: the poor are not “bankable” because traditional banking requires collateral they don’t have. The genius was in the design of the solution. Grameen pioneered “social collateral” and group lending. Borrowers, predominantly women, formed small groups who guaranteed each other’s loans. Repayment wasn’t just a financial obligation; it was a social contract of mutual support and accountability. This model turned the entire banking logic on its head. The trust that conventional banks placed in assets was instead placed in community.
The results spoke volumes. Grameen Bank reported repayment rates that would be the envy of many commercial lenders. More importantly, the ripple effects began to transform villages. The women who received loans—often the most marginalized members of society—started small businesses, earned income, sent their children to school, and became decision-makers in their households. Microfinance, the umbrella term for these services, evolved from simple microcredit to include savings accounts, insurance, and fund transfers, creating a basic financial toolkit for those excluded from the formal economy.
A Model That Caught Fire
The story of Grameen was too powerful to remain confined to Bangladesh. Its principles of trust, community, and financial inclusion resonated globally, sparking a movement. The model was adapted and replicated in over 64 countries, from rural villages in Bolivia to bustling towns in the Philippines. It became a foundational pillar of development economics, offering a tangible tool to fight the stark inequality represented by the fact that about 1.4 billion adults worldwide remain “unbanked.”
The focus on women was particularly transformative. By deliberately targeting female borrowers, Grameen and its imitators began to chip away at deep-seated gender inequities. When women control resources, studies show, families are healthier, children are better educated, and communities grow more resilient. Microfinance, in this light, became one of the largest-scale feminist development experiments in history, quietly shifting power dynamics one small business at a time.
The Hard Questions: Beyond the Headlines
No revolution follows a straight line, and the microfinance movement was no exception. In the years following the 2006 Nobel spotlight, the sector faced a reckoning. The very success of the idea attracted profit-driven commercial lenders whose focus on scale and returns sometimes overshadowed the original social mission. Reports of over-indebtedness and aggressive collection practices emerged from some corners of the world, leading to a “backlash” and prompting a critical question: Had the hype outrun the reality?
Researchers also began to grapple with the challenge of measuring impact. While individual success stories were abundant, establishing a clear, causal link between microfinance loans and large-scale poverty reduction proved elusive. Does a small loan truly lift someone from poverty, or does it merely help them cope with it more smoothly? The answer, it turns out, is complex. The consensus that emerged is that microcredit alone is not a magic bullet. For deeper impact—transformative change that truly alters a life’s trajectory—financial services often need to be coupled with “plus” services: training, health education, and mentorship. The $27 loan was a key, but it sometimes needed other tools to unlock the door to a better future.
Furthermore, the Nobel Committee’s leap from economics to peace remained largely unproven. While there are strong intuitive links—economic stability reduces desperation, and women’s empowerment fosters more peaceful communities—the empirical evidence connecting microfinance directly to conflict prevention is still an open field of study. The award was a hypothesis about the roots of peace, written not in treaty ink but in the ledger books of the world’s smallest entrepreneurs.
The Unfinished Revolution
Today, the legacy of the 2006 Nobel Prize is a living, breathing entity. It’s a story of profound inspiration that sparked a global movement. It’s also a story of sobering lessons about the complexities of development and the perils of oversimplification. Muhammad Yunus’s work proved that the entrepreneurial spirit is not a privilege of the wealthy, and that a system built on trust can unlock astonishing potential.
The journey from that first $27 loan is a testament to the power of an idea whose time has come. It reminds us that progress is often born from listening to those on the margins and asking what they need to build their own future. The future of microfinance lies in integrating those lessons—blending financial access with education, harnessing technology for greater reach, and never losing sight of the individual human dignity at its core.
The 2006 Nobel Peace Prize didn’t award a solution; it awarded a starting point. It gave the world a compelling model for “development from below.” As we look ahead, the open question remains: How can we build upon this foundation not just to manage poverty, but to dismantle its architecture, one empowered life at a time? The next chapter is still being written, not by economists or committees, but by the millions of people using a small loan as a stepping stone to a future they once thought impossible.